
Can Covariance Be Zero?

Unlike Variance, Which Is Non-Negative, Covariance Can Be Negative or Positive (Or Zero, of Course). a Positive Value of Covariance Means That Two Random...
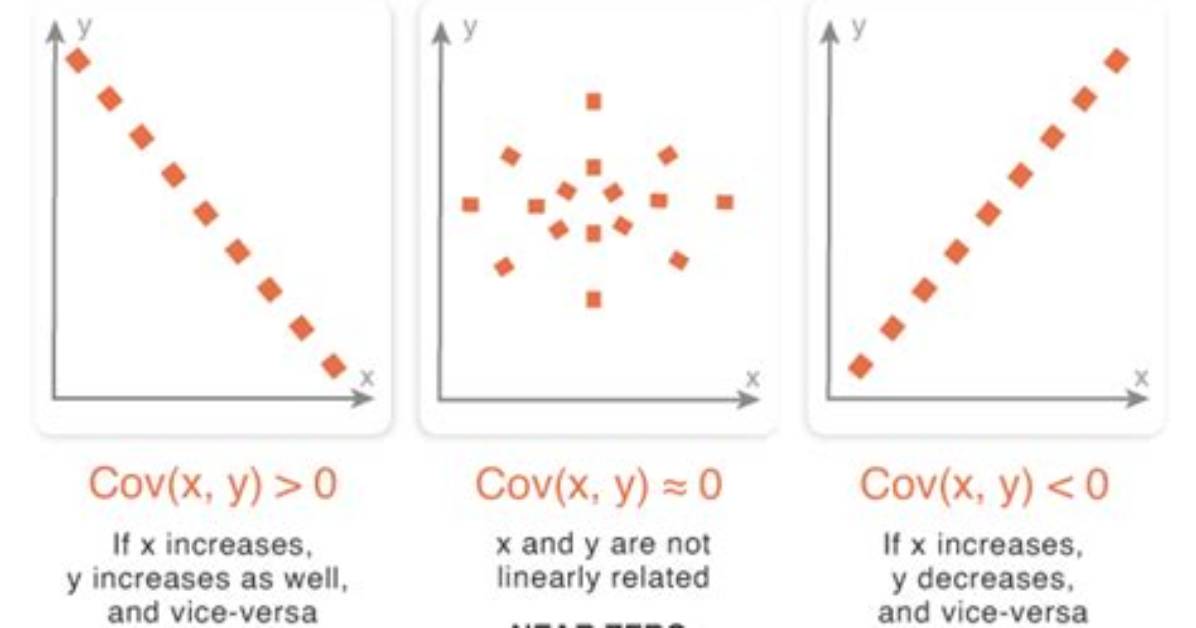
Unlike Variance, which is non-negative, Covariance can be negative or positive (or zero, of course). A positive value of Covariance means that two random variables tend to vary in the same direction, a negative value means that they vary in opposite directions, and a 0 means that they don't vary together.
What happens when covariance is 0?
The covariance is defined as the mean value of this product, calculated using each pair of data points xi and yi. If the covariance is zero, then the cases in which the product was positive were offset by those in which it was negative, and there is no linear relationship between the two random variables.
Is covariance always zero?
Covariance can be positive, zero, or negative. ... If X and Y are independent variables, then their covariance is 0: Cov(X, Y ) = E(XY ) − µXµY = E(X)E(Y ) − µXµY = 0 The converse, however, is not always true. Cov(X, Y ) can be 0 for variables that are not inde- pendent.
Sarah Jenkins is a veteran tech journalist with over 12 years of experience covering artificial intelligence, mobile innovations, and digital ethics. Her insights have appeared in leading technology publications worldwide.
