
Does Kelly Criterion Work?

Although It's One of Many Tried and Tested Staking Methods, the Kelly Criterion Is Seen as the Best Due to the Fact That It Protects Your Bankroll While Still...
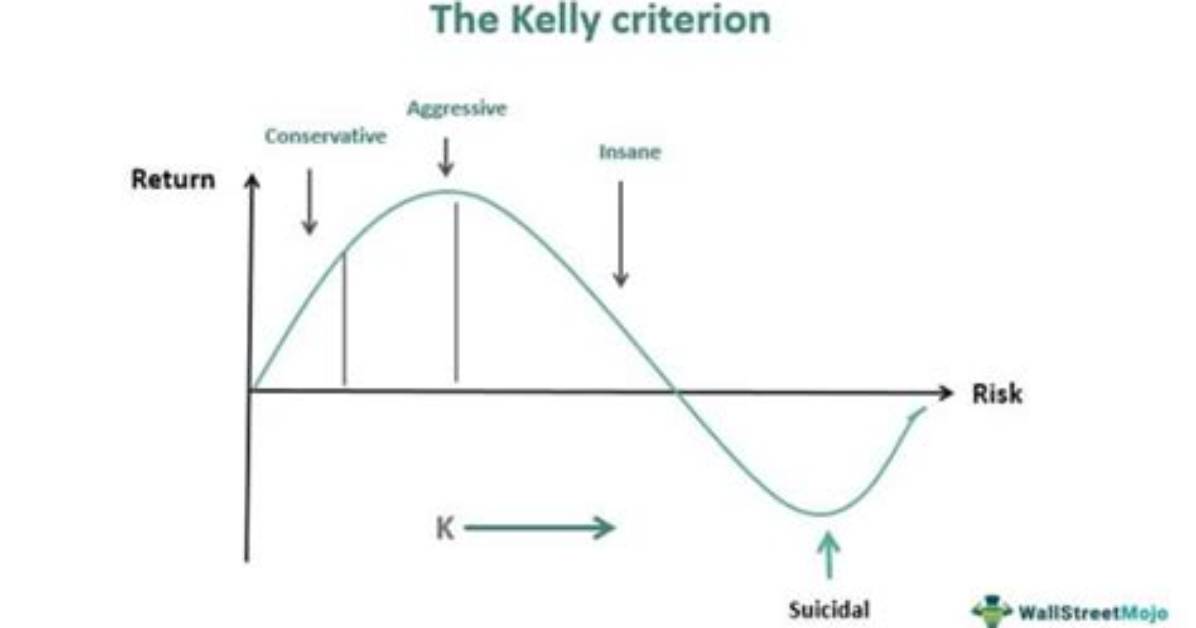
Although it's one of many tried and tested staking methods, the Kelly Criterion is seen as the best due to the fact that it protects your bankroll while still ensuring you stake funds that are proportionate to the positive expected value (or “edge”) that you have over the market.
Is Kelly Criterion optimal?
In probability theory, the Kelly criterion (or Kelly strategy or Kelly bet), is a formula that determines the optimal theoretical size for a bet. ... The practical use of the formula has been demonstrated for gambling and the same idea was used to explain diversification in investment management.
How is Kelly Criterion calculated?
It is popular due to how it typically leads to higher wealth in the long run compared to other types of strategies. It is based on the formula k% = bp–q/b, with p and q equaling the probabilities of winning and losing, respectively.
Sophia analyzes international trade, startup ecosystems, retail transformation, and supply chain logistics for modern digital publications.
