
How Do I Write off Inventory in Quickbooks?

Can I Write off Expired Inventory? Select New? . Under Other, Select Inventory Qty Adjustment. Enter the Adjustment Date. in the Inventory Adjustment Account...
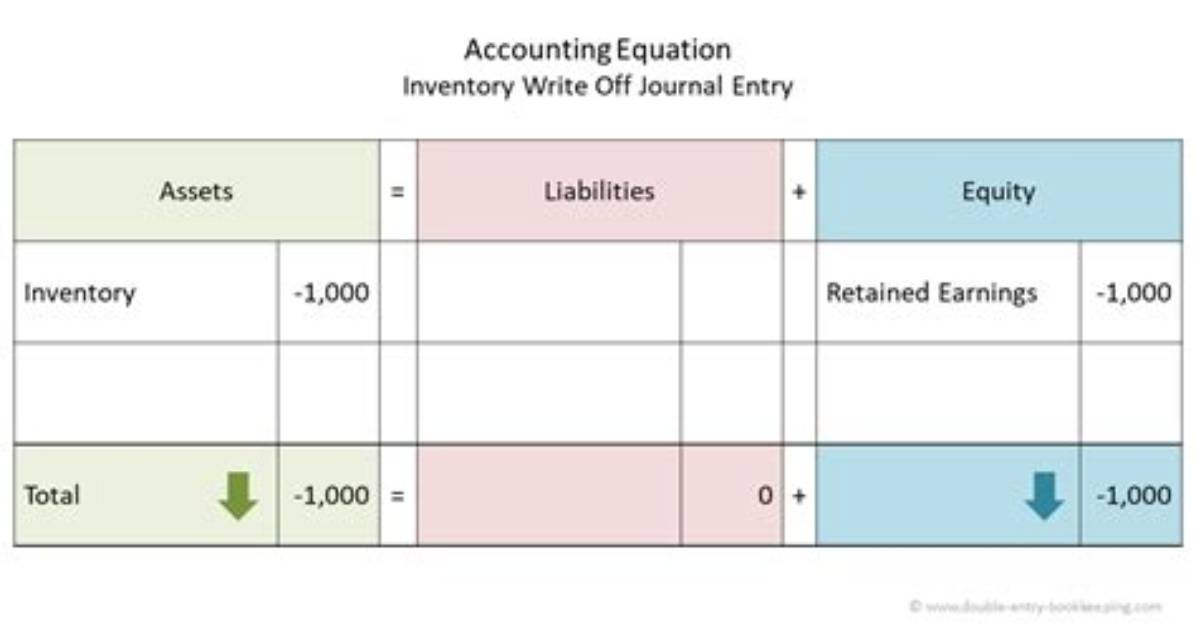
- Select New ?.
- Under Other, select Inventory Qty Adjustment.
- Enter the Adjustment Date.
- In the Inventory adjustment account drop-down, select the appropriate account.
- Select the products in the Product field drop-down.
- For each item, enter either a new quantity or a change in quantity.
.
Furthermore, how do I write off inventory in QuickBooks desktop?
On the first Line: Under Account, select Sales of Product Income. Under Debits, enter the amount you are writing off.
This removes the Income, credits the customer in Accounts Receivable, and credits Cost of Goods to record the Expense.
- Select the + New button.
- Select Journal Entry.
- Enter the date.
Additionally, how do you write off damaged inventory? At the end of the month, you write off the damaged inventory by debiting the cost of goods sold account and crediting the inventory contra account. However, if you infrequently have damaged inventory, you can debit the cost of goods sold account and credit the inventory account to write off the loss.
Consequently, how do I deduct inventory in QuickBooks?
Deducting items from inventory when it is included in a Bundle.
- Click Sales.
- Select Products and Services.
- Click New.
- Choose Bundles.
- Add the single items.
- Click Save and close.
How do I use inventory in QuickBooks?
Open QuickBooks, click "Edit" in the menu bar and select "Preferences." Click "Items & Inventory," and then click the "Company Preferences" tab. Click the box next to "Inventory and purchase orders are active" to enable inventory tracking. Click "OK."
