
How Do You Recapture Depreciation

Depreciation Recapture Is Assessed When the Sale Price of an Asset Exceeds the Tax Basis or Adjusted Cost Basis. the Difference Between These Figures Is Thus...
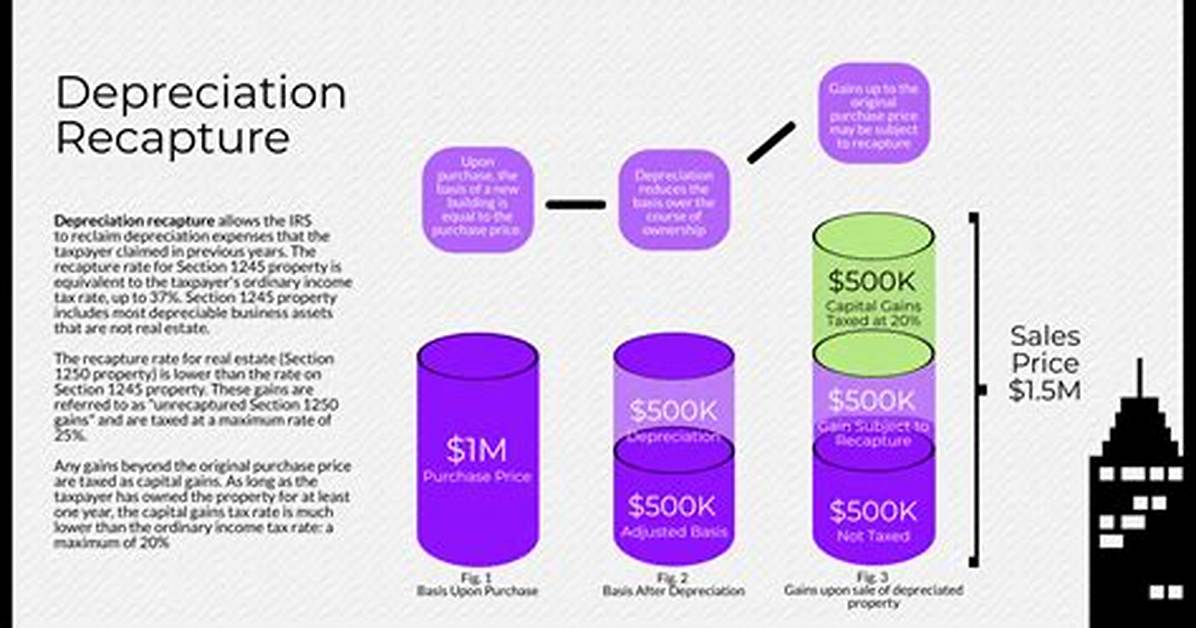
Depreciation recapture is assessed when the sale price of an asset exceeds the tax basis or adjusted cost basis. The difference between these figures is thus “recaptured” by reporting it as ordinary income. Depreciation recapture is reported on Internal Revenue Service
How do you calculate depreciation recapture?
Subtract the taken or allowable depreciation expense from your original cost basis. This amount is your adjusted cost basis. For example, if you paid $10,000 for a tractor and took $4,000 in depreciation expenses, your new adjusted cost basis would be $10,000 minus $4,000, or $6,000.
How do you calculate recapture?
Start with your UCC in any class and add the amount you spent on new property in the class. Then, subtract the proceeds you earned from the disposition of property in that class.
Marcus Vance is a cybersecurity auditor and technology writer dedicated to educating the public about online safety, data privacy regulations, enterprise security, and emerging cyber threats.
