
On Cumulative Abnormal Return?

A Cumulative Abnormal Return (Car) Is the Sum Total of All Abnormal Returns and Can Be Used to Measure the Effect Lawsuits, Buyouts, and Other Events Have on...
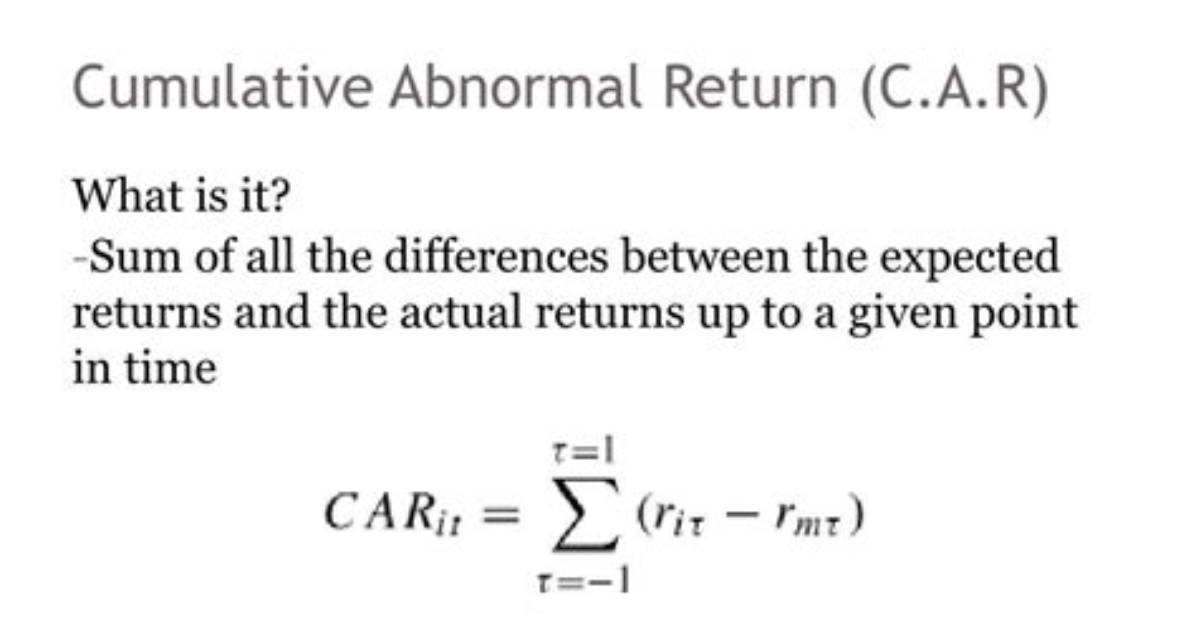
A cumulative abnormal return (CAR) is the sum total of all abnormal returns and can be used to measure the effect lawsuits, buyouts, and other events have on stock prices.
How do you test the significance of a cumulative abnormal return?
To test the significance of the Cumulative Abnormal Return's (CAR's), one must calculate the variance of the aggregated AR's across firms and then sum this number for each observation in the event window to achieve the variance of the CAR's, and then use the square root of this as the denominator in the t-statistic.
How do you comment on abnormal return?
The abnormal return on an investment is calculated as follows (1): RAbnormal = RActual – RNormal An investment's abnormal return could be positive or negative. It essentially measures how the stock or a fund has performed over a given period of time.
Sophia analyzes international trade, startup ecosystems, retail transformation, and supply chain logistics for modern digital publications.
