
Python - Yield to Maturity (Finance - Bonds)

I Am Trying to Calculate the Yield to Maturity for Bonds (Working in Google Colab (Jupyter)). the Mathematical Formulation of the Problem Is: with Price =...
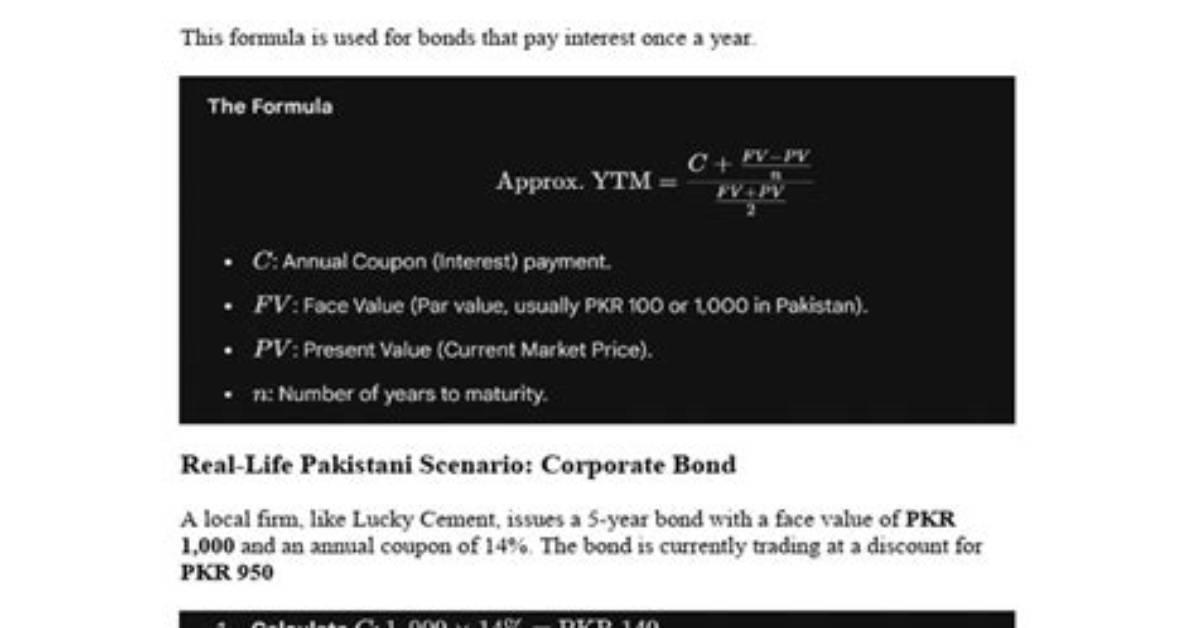
I am trying to calculate the yield to maturity for bonds (working in Google Colab (Jupyter)). The mathematical formulation of the problem is: with price = $1276.76, number of periods = 60 [0.5 years] = 30 years, payment per period = $40 and final payment(par value) = $1000 and interest rate = r.
Where I am trying to derive the "r" through a function.
When going for an approach with hardcoding the formula and function I found herefore:
# Yield to maturity

""" Get yield-to-maturity of a bond """
import scipy.optimize as optimize


def bond_ytm(price, par, T, coup, freq=2, guess=0.05):
    freq = float(freq)
    periods = T*freq
    coupon = coup/100.*par/freq
    dt = [(i+1)/freq for i in range(int(periods))]
    ytm_func = lambda(y): \
        sum([coupon/(1+y/freq)**(freq*t) for t in dt]) + \
        par/(1+y/freq)**(freq*t) - price

    return optimize.newton(ytm_func, guess)
from bond_ytm import bond_ytm
ytm = bond_ytm(95.0428, 100, 1.5, 5.75, 2)
print(ytm)
I get the error: "invalid syntax" in the lambda line and when removing it (in order to check if the function itself works) "no module named 'bond_ytm'" even saving it as extra file in the same directory as (.jpynb) python file. I did also not understand the lambda in-line function, the dt array/for-loop, and where and why the bond_ytm is called from.
Here is a very similar approach form github, which also did not run, using another function for the second part:
if __name__ == "__main__":
    ytm = bond_ytm(95.0428, 100, 1.5, 5.75, 2)
    print ytm
And which left me with the same missing understanding.
Here is a large documentation to a package, where I can't know their methodology of calculation, but where I can enter the dates of the period manually and which allows for computing accrued interest between the payment (coupon) dates. :
>>> bond_yield(settle="2012-04-15", mat="2022-01-01", cpn=8e-2,
... price=94.33, freq=1)
0.08884647275135965

>>> bond_yield(mat=10.25, cpn=8e-2, price=93.37, freq=2)
0.09000591604105035

>>> bond_yield(settle="2012-04-15", mat="2022-01-01", cpn=8e-2,
... price=[93, 94, 95], freq=1)
array([0.09104904, 0.08938905, 0.08775269])
1 Answer
If what you want to find is the internal rate of return, there is a numpy financial library (that needs to be installed with pip) that will find that.
>>> import numpy_financial as npf
>>> npf.irr([-1276.76] + [40]*60 + [1000])
0.02985264673122634
Marcus Vance is a cybersecurity auditor and technology writer dedicated to educating the public about online safety, data privacy regulations, enterprise security, and emerging cyber threats.
