
Unearned Ufmip Refund

Unearned Ufmip. Dollar Amount of Upfront Mortgage Insurance Premium (Ufmip) That Was Not Earned by Hud for the Prior Fha-Insured Mortgage. How Do You Calculate...
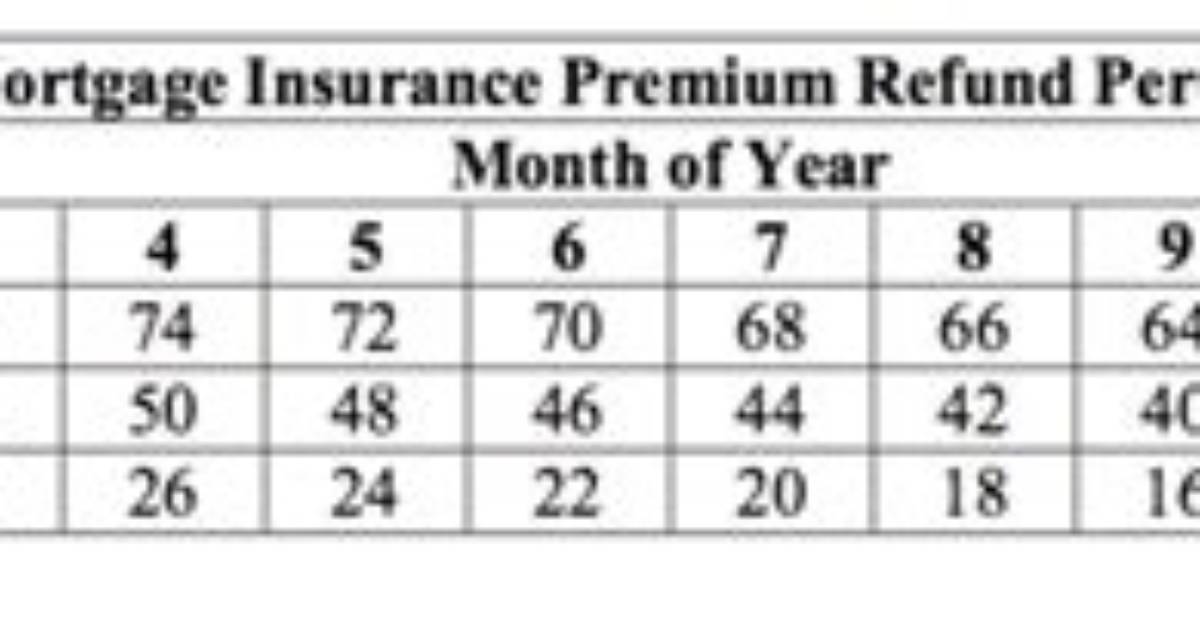
Unearned UFMIP. Dollar amount of upfront mortgage insurance premium (UFMIP) that was not earned by HUD for the prior FHA-insured mortgage.
How do you calculate Ufmip refund?
Your MIP refund amount.
This amount is the total UFMIP you owe on your new refinance loan. For example, if your new refinance loan is $200,000, then your new UFMIP amount is $3,500 ($200,000 x 0.175).
Can I get a refund on my PMI?
When PMI is canceled, the lender has 45 days to refund applicable premiums. That said, do you get PMI back when you sell your house? It’s a reasonable question considering the new borrower is on the hook for mortgage insurance moving forward. Unfortunately for you, the seller, the premiums you paid won’t be refunded.
Do I have to pay Ufmip?
UFMIP protects the lender in case you default on your mortgage payments. FHA loans require down payments as low as 3.5%. In exchange for the low down payment, you must pay UFMIP on your FHA loan and a mortgage insurance premium (MIP).
Is Ufmip considered a closing cost?
The Up Front Mortgage Insurance Premium (UFMIP) is also a closing cost the borrower needs to pay unless the borrower wants to consider financing the UFMIP-something only permitted if the applicant chooses to finance the entire amount.
Is MIP refund based on closing date or funding date?
Any refinance credit (upfront MIP that was paid but not earned by HUD) from the prior case is applied to the new case when an upfront MIP payment is submitted for the new case. The refinance credit amount is based on the closing or disbursement date provided for the new mortgage.
How do I get rid of my MIP?
If you currently pay PMI or MIP mortgage insurance, you can get rid of it by refinancing once your home reaches 20 percent equity. If you’re shopping for a new home loan, look for options that allow no PMI even without 20 percent down.
What is the difference between PMI and MIP?
The main difference between PMI and MIP, as we’ve already mentioned, is that PMI applies to conventional loans while MIP applies to FHA loans.
Where does the PMI money go?
The PMI fee goes toward insurance coverage that protects your lender—not you—in case you can’t make monthly payments and default on your loan. Your lender then can foreclose your house and auction it off to earn back the money they loaned you. At a foreclosure auction, lenders can recover about 80% of a home’s value.
What is mortgage insurance refund?
“If the Borrower is refinancing their current FHA-insured Mortgage to another FHA- insured Mortgage within 3 years, a refund credit is applied to reduce the amount of the Upfront Mortgage Insurance Premium (UFMIP) paid on the refinanced Mortgage, according to the refund schedule…”
Is PMI paid through escrow?
Lenders use PMI to protect their losses should you default on the house. Your PMI payment is paid into an escrow account and issued to the appropriate creditor by your lender when it’s due.
How do I claim my FHA refund?
Requesting a Refund
On the FHA Connection, go to the Upfront Premium Collection menu and select Request a Refund in the Pay Upfront Premium section. The Upfront Refund Request page appears for entering refund information.
What is FHA Ufmip funding fee?
An FHA UFMIP/VA Funding Fee is an upfront payment attached to federal mortgage lending for both military veterans and citizens. These payments are designed to help offset some of the default risk attached to these mortgages.
Is FHA Ufmip tax deductible?
You can deduct the UFMIP if you opted for the latter method – the out-of-pocket lump sum payment at closing. Your adjusted gross income, or AGI, must also meet IRS limits. Furthermore, you must occupy the home as your principal or secondary residence.
Can you pay Ufmip at closing?
The main difference between the two types of insurance premiums is that the UFMIP is a one-time payment due at closing, whereas the AMIP is an ongoing monthly expense.
Is upfront MIP in closing costs?
Like most mortgages, FHA loans usually come with closing costs paid by the borrower. Many of these costs are similar to the closing costs for other types of mortgages, including lender and third-party fees. The Upfront Mortgage Insurance Premium is a closing cost unique to FHA loans, however.
Do you have to pay upfront MIP?
Upfront mortgage insurance premium (MIP) is required for most of the FHA’s Single Family mortgage insurance programs. Lenders must remit upfront MIP within 10 calendar days of the mortgage closing or disbursement date, whichever is later.
Must Read
Postos Recomendados
David Miller brings 15 years of experience in global economics, personal finance strategy, and market dynamics. He specializes in turning complex economic trends into actionable insights for everyday readers.
