
Was Cash Conversion Cycle?

In Management Accounting, the Cash Conversion Cycle Measures How Long a Firm Will Be Deprived of Cash If It Increases Its Investment in Inventory in Order to...
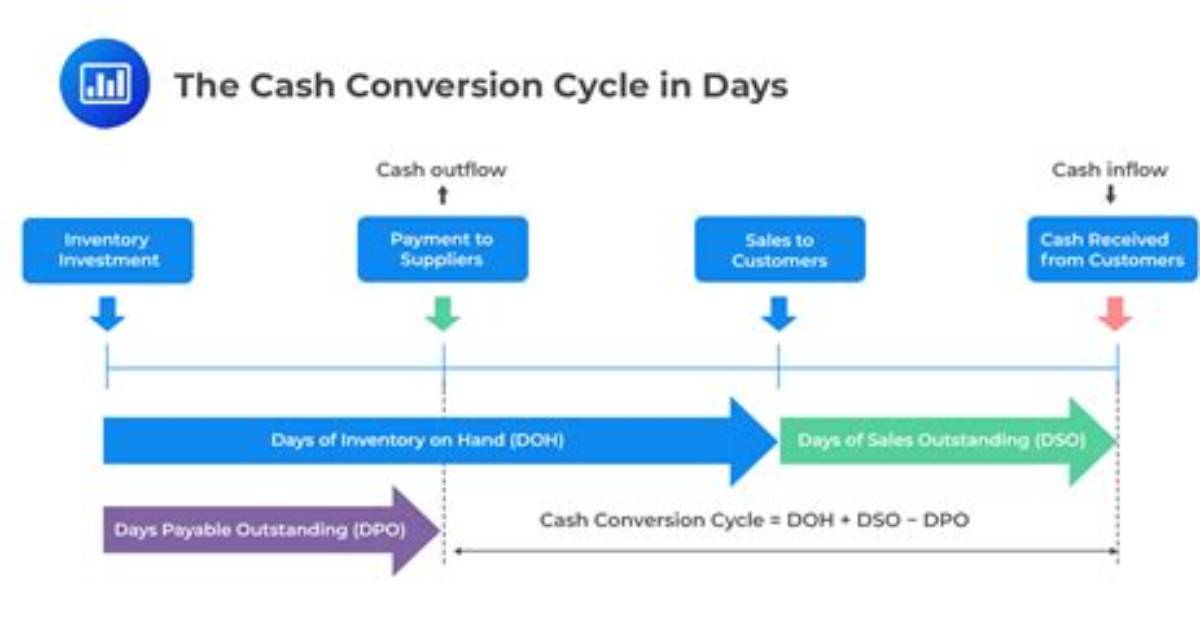
In management accounting, the Cash conversion cycle measures how long a firm will be deprived of cash if it increases its investment in inventory in order to expand customer sales. It is thus a measure of the liquidity risk entailed by growth.
What is meant by cash conversion cycle?
The cash conversion cycle (CCC) is a metric that expresses the length of time (in days) that it takes for a company to convert its investments in inventory and other resources into cash flows from sales.
How do you calculate cash conversion cycle?
- CCC = Days of Sales Outstanding PLUS Days of Inventory Outstanding MINUS Days of Payables Outstanding.
- CCC = DSO + DIO – DPO.
- DSO = [(BegAR + EndAR) / 2] / (Revenue / 365)
- Days of Inventory Outstanding.
- DIO = [(BegInv + EndInv / 2)] / (COGS / 365)
- Operating Cycle = DSO + DIO.
Chloe Bennett explores the intersection of pop culture, streaming entertainment, digital trends, and contemporary lifestyle. Her weekly commentary reaches thousands of culture enthusiasts.
