
What Is a Sample in Audit

Audit Sampling Is the Use of an Audit Procedure on a Selection of the Items Within an Account Balance or Class of Transactions. the Sampling Method Used Should...
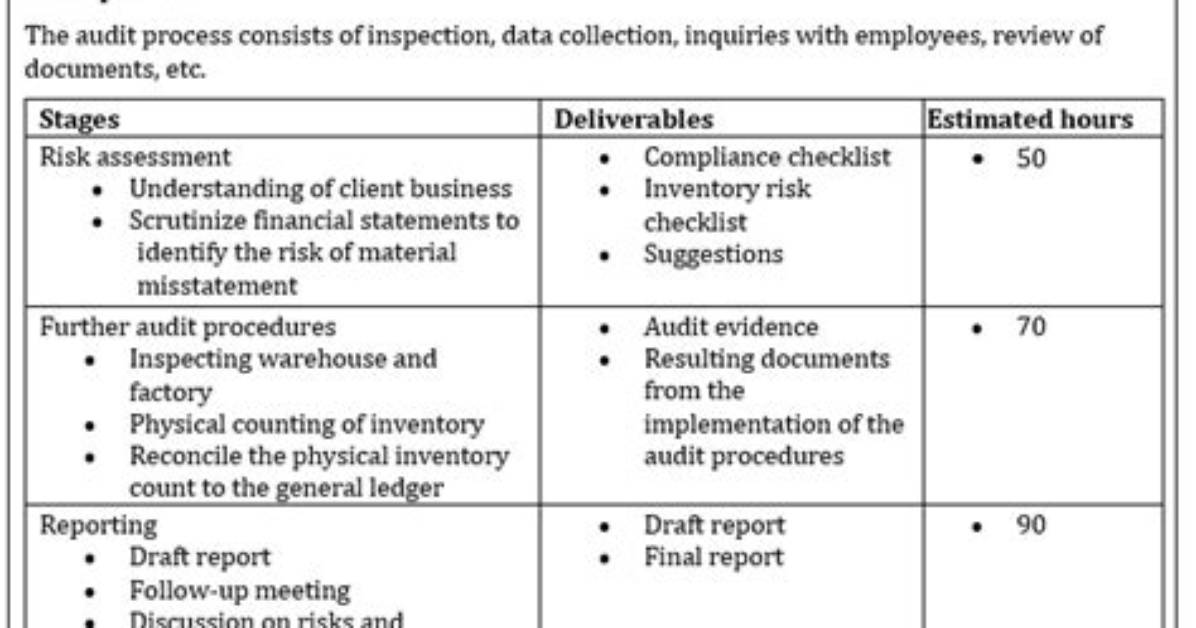
Audit sampling is the use of an audit procedure on a selection of the items within an account balance or class of transactions. The sampling method used should yield an equal probability that each unit in the sample could be selected. The intent behind doing so is to evaluate some aspect of the information.
What is audit sampling and why sample is taken?
Audit sampling enables auditors to make conclusions and express fair opinions based on predetermined objectives without having to check all of the items within financial statements. The auditors will only verify selected items, and through sampling, can infer their opinion on the entire population of items.
When should you increase audit sample size?
1. An increase in the auditor’s assessment of the risk of material misstatement Increase The higher the auditor’s assessment of the risk of material misstatement, the larger the sample size needs to be. The auditor’s assessment of the risk of material misstatement is affected by inherent risk and control risk.
Sarah Jenkins is a veteran tech journalist with over 12 years of experience covering artificial intelligence, mobile innovations, and digital ethics. Her insights have appeared in leading technology publications worldwide.
