
What Is Matching Concept in Accounting? Top 9 Facts About It

Accounting Is the Language of Business. a Good Accountant Understands How to Use Accounting Principles and Concepts to Help Businesses Succeed. but It Can Be...
Accounting is the language of business. A good accountant understands how to use accounting principles and concepts to help businesses succeed.
But it can be hard for new accountants to learn this language, especially if they don’t have a background in finance or business. This makes it difficult for them to communicate with their clients clearly about what financial information means.
What Is Matching Concept In Accounting will teach you everything you need to know about accounting principles without getting too technical or boring, so that you can start using them right away on your own projects!
What Is Matching Concept in Accounting?
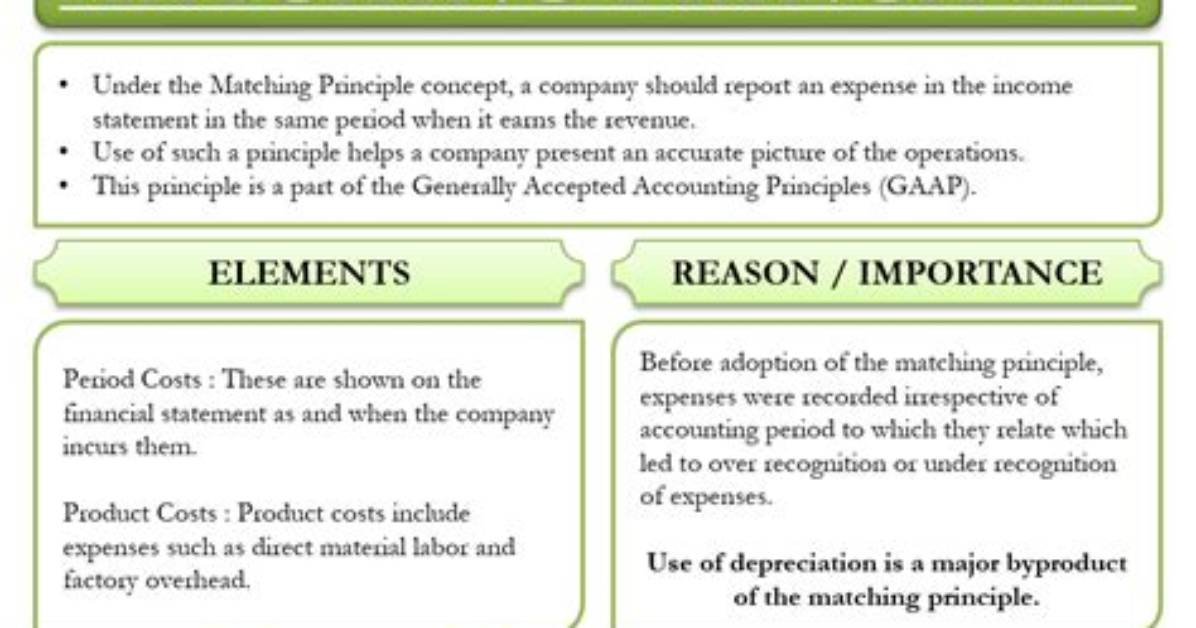
The matching concept is a fundamental accounting principle that can be used to determine what expenses go with what revenue and what expenses should be deferred. To understand better what the matching concept entails, it is important first to understand both what belongs on an income statement and what belongs on a balance sheet.
Accounting transactions such as buying supplies, selling goods or providing services all belong on an income statement. The matching concept represents the idea that some expenses must be put onto an income statement in the same period they create revenue. For instance, if you buy office supplies for your business but do not sell anything until next year, those sales would not be made against a current expense because you have yet to generate any revenue from them.
Therefore, the cost of supplies should be recorded as a current asset rather than a current expense. There are two primary reasons for this:
- Expenses must match the correct time period to fit into what is known as accrual accounting, which means that transactions must be recorded at the same time they take place whether or not those expenses have been paid yet, and
- Expenses create future revenue by creating what is known as a sunk cost. In other words, costs cannot be recovered once incurred so it does nobody any good to have an invoice sitting around unpaid until next year because then it will just become dead weight that can’t contribute to revenue. The important thing is to classify all the different types of inventory correctly in relation to what makes sense based on what might happen with those supplies. In this way, some expenses are classified as current and others as non-current because they cannot be charged to expense until some point in the future even though those costs have been incurred already.
Example of Matching Principle
For example, suppose you buy a supply of paper for your business that is predicted to last for two years before needing to be replenished. If it turns out that the supply only lasts one year, then the matching concept dictates what must happen: The cost of that inventory will either be removed from an asset account on a balance sheet or added into an expense account on an income statement assuming it’s still relevant either way.
In fact, if more of what you bought ends up being used than was expected, your company cannot take what is known as a loss on the difference. Rather, it must either remove what would be considered obsolete inventory from an asset account or move what remains into that same asset account.
On the other hand, if what you bought lasts longer than expected, then what was once thought to be obsolete can be moved back into an asset account where it will remain until it ultimately reaches the point where you need to make another purchase of supplies or services like it next time around.
This is what makes the matching principle so important for businesses to understand: It’s not simply about what belongs on revenue and what belongs on expenses; rather, whether something ends up becoming current versus non-current depends on how much of what you bought has been consumed over what amount of time.
In short, what you have purchased must be included in the same account as what it was acquired to eventually replace or what that item will contribute to revenue in some way. In this respect, the matching concept acts as a bridge between what would normally be called an expense and what can still be counted as an asset even though it cannot generate immediate revenue from the items being purchased.
Although this might sound complicated at first glance because there are so many different types of inventory involved, once you grasp what is classified as current versus non-current within a financial statement, it becomes much easier to understand why certain expenses go with certain revenue even though they were incurred at different times during a fiscal year which has—in its own right—already passed.
David Miller brings 15 years of experience in global economics, personal finance strategy, and market dynamics. He specializes in turning complex economic trends into actionable insights for everyday readers.
