
When to Stop Capitalising Borrowing Costs?

Capitalization of Borrowing Cost Ceases When All the Activities Necessary to Prepare the Qualifying Assets Are Complete. If an Asset Has Been Completed in...
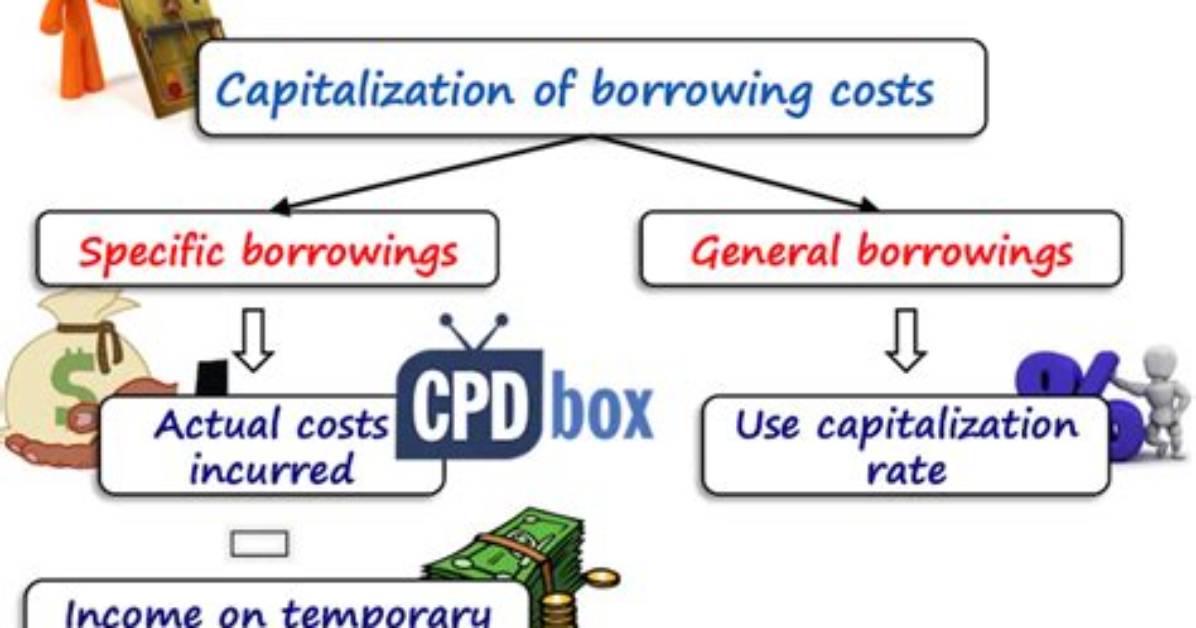
Capitalization of borrowing cost ceases when all the activities necessary to prepare the qualifying assets are complete. If an asset has been completed in parts and a completed part is capable of being used while the construction for the other part continues then the capitalization for that completed part will cease.
When should the capitalization of borrowing cost cease?
Capitalisation of borrowing costs should be suspended during extended periods in which active development of a qualifying asset is suspended (IAS 23.20). Capitalisation of borrowing costs is suspended when, for example, the entity needs to redirect its workforce and efforts to development of another asset.
Under what conditions can an entity Capitalise borrowing costs?
An entity shall capitalise borrowing costs that are directly attributable to the acquisition, construction or production of a qualifying asset as part of the cost of that asset. An entity shall recognise other borrowing costs as an expense in the period in which it is incurred.
Sophia analyzes international trade, startup ecosystems, retail transformation, and supply chain logistics for modern digital publications.
