
When to Write off Inventory?

Writing off Inventory Involves Removing the Cost of No-Value Inventory Items from the Accounting Records. Inventory Should Be Written off When It Becomes...
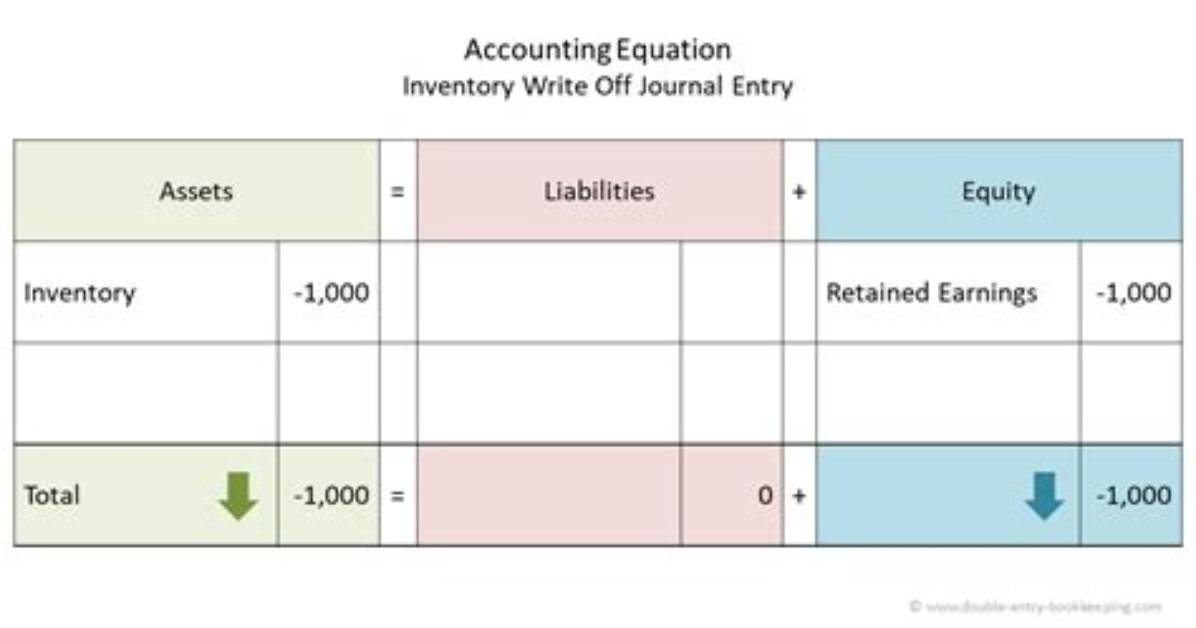
Writing off inventory involves removing the cost of no-value inventory items from the accounting records. Inventory should be written off when it becomes obsolete or its market price has fallen to a level below the cost at which it is currently recorded in the accounting records.
When Should inventory be written down?
Inventory is written down when goods are lost or stolen, or their value has declined. This should be done at once, so that the financial statements immediately reflect the reduced value of the inventory.
Why would you write off inventory?
Inventory write-offs are done to support accounting accuracy objectives while also reducing the tax liability for business owners. It's done by charging it to the cost of goods sold or by balancing the obsolete inventory allowance in the books.
Chloe Bennett explores the intersection of pop culture, streaming entertainment, digital trends, and contemporary lifestyle. Her weekly commentary reaches thousands of culture enthusiasts.
