
Why Expected Shortfall Is Better Than Var?

A Measure That Produces Better Incentives for Traders Than Var Is Expected Shortfall. for Example, with X = 99 and N = 10, the Expected Shortfall Is the...
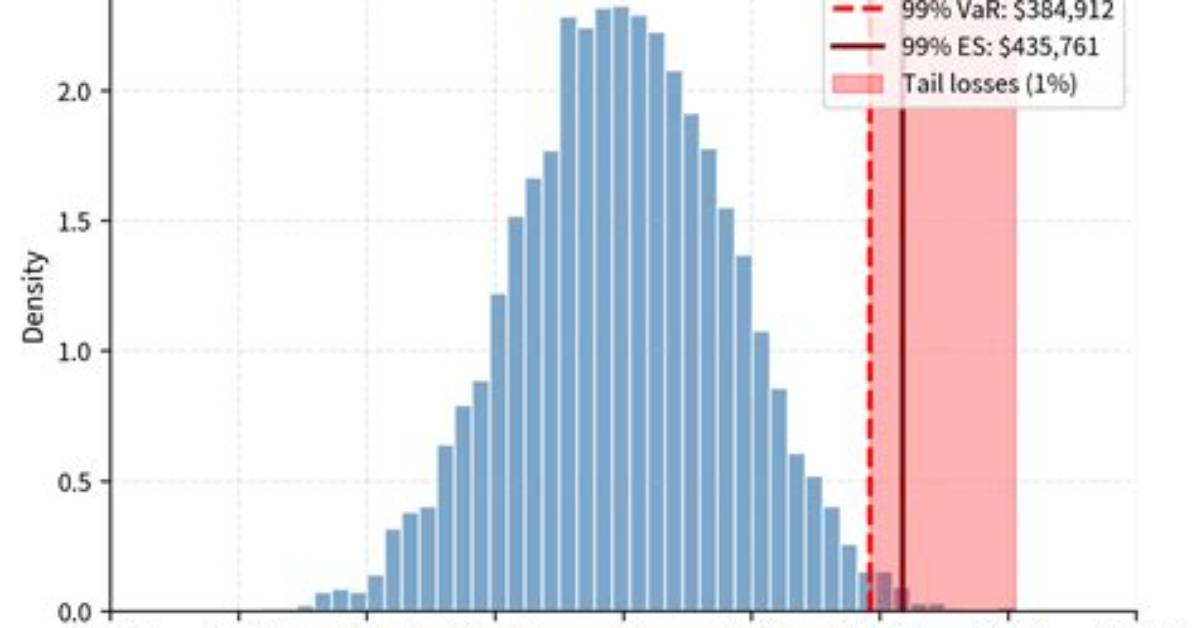
A measure that produces better incentives for traders than VAR is expected shortfall. For example, with X = 99 and N = 10, the expected shortfall is the average amount that is lost over a 10-day period, assuming that the loss is greater than the 99th percentile of the loss distribution. ...
Is expected shortfall always greater than VaR?
The measures
Expected Shortfall (ES) is the negative of the expected value of the tail beyond the VaR (gold area in Figure 3). Hence it is always a larger number than the corresponding VaR.
What does expected shortfall represent?
Expected Shortfall is a risk measure that shows the amount of loss if the loss exceeds VaR. Expected Shortfall is known by other names, such as tail VaR, CVaR, and tail loss. Expected Shortfall tells how bad portfolio losses will be if the losses exceed Value at Risk.
Sophia analyzes international trade, startup ecosystems, retail transformation, and supply chain logistics for modern digital publications.
